Safety
Risks that follow a betting app and a UPI payment
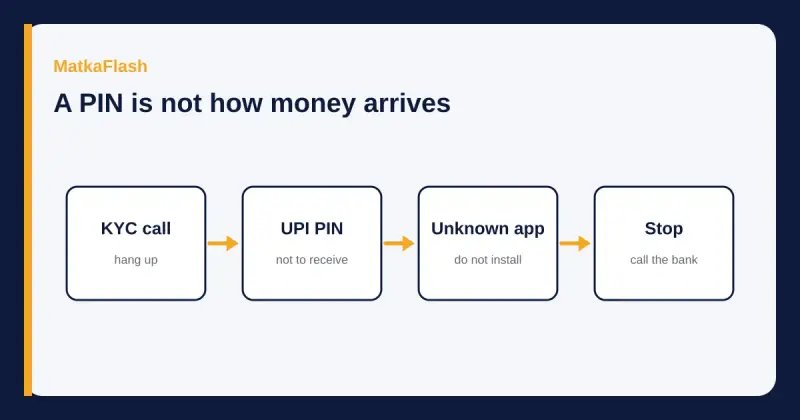
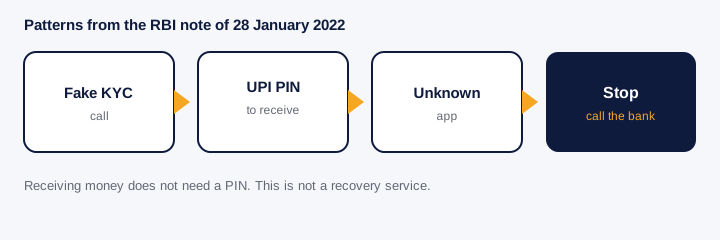
The Reserve Bank's 28 January 2022 note describes calls, unknown apps and a UPI PIN asked so that money can be 'received'. Those patterns do not become safe because the app shows a matka chart.
Key points
- The RBI says not to share a UPI PIN, OTP, password or card number, including with someone who claims to be the bank.
- A call that threatens to block the account unless you update KYC is a pattern the RBI names.
- Receiving money does not need a UPI PIN or a QR scan. Being asked for either is a warning.
- An unknown app can read what is on the phone. Do not install one to see a result.
- This page does not name a safe betting app. It does not offer account recovery.
Contents
A chart app that also takes a payment is no longer only a chart. The money path is the part that can empty an account, and it is the part a public advisory already describes without mentioning matka at all. This page stays inside that advisory. It does not add a statistic the advisory does not give, it does not name a bookie, and it does not print a helpline other than the mental-health line already on every guide. For the costume of a fake result page, read the fake-site guide.
| Pattern the RBI names | The precaution it states |
|---|---|
| A call pretending to be the bank, a wallet or a phone company, often about KYC | Do not share the PIN, OTP or password. Open the bank's own site or branch. |
| A mail or SMS with a link that looks like the bank | Check the address. Do not enter card or UPI details on it. |
| An app that can see the phone, offered as help | Do not download an unknown app. |
| A collect request that says to enter the UPI PIN to receive money | Receiving money does not need a PIN or a QR scan. |
| A phone number found on a search result, claiming to be the bank | Take the number from the bank's own website. |
UPI, the PIN, and money that was supposed to arrive
The press release, number 2021-2022/1630, is titled Consumer Awareness – Cyber Threats and Frauds and is dated 28 January 2022. It says fraudsters want the login, the password, the OTP, the card PIN, the CVV and the expiry. One method it names is misuse of the UPI collect request: a fake request whose text says to enter the UPI PIN in order to receive money. The safe-practice list then says that a transaction in which you receive money does not require scanning a barcode or a QR code, or entering an MPIN. If a betting app, a 'withdrawal' screen or a stranger asks for the PIN so that winnings can be credited, that is the pattern the Reserve Bank described. Entering the PIN sends money. It does not release money.
The same list says never to share the UPI PIN, OTP or card details with anyone, not even with a person who sounds like a bank official. A result site that asks for those details to 'verify a payout' is asking for the keys. MatkaFlash does not take a payment and does not ask for a UPI PIN. A page that does is not this record.
KYC calls and a frozen-account story
The release describes vishing: a phone call pretending to be a bank, a wallet or a phone company, using KYC update, unblocking an account or a SIM, or crediting a debited amount as the pretext. It says a call or mail that threatens to block the account unless KYC is updated, and then offers a link, is a common method. The precaution is to refuse the link and to use the official site or the branch. This page does not add a rule about how many days a bank keeps a hold, because the release does not give one. If a bank has restricted an account, the person to ask is the bank, through a number from the bank's own site, not a number from a search ad or from the app that took the payment.
A betting app can also be the place the card or UPI mandate was approved. The release tells people who see a debit they did not make to tell the bank or wallet at once and to block debit modes, including UPI. That is the public instruction. This site cannot block an account, reverse a transfer, or see a bank ledger. Anyone who promises that, for a fee, is a second payment on top of the first.
Unknown apps, remote access, and loan apps
The release's remote-access item is a person who persuades the customer to install an application that can reach the data on the phone or the computer. The precaution is direct: do not download an unknown app, because it may read confidential data. A chart file, a 'live result APK', or a screen-share session offered so someone can 'guide the withdrawal' fits that sentence. The fake-site checklist says the same thing from the result page's side.
Loan apps are a neighbouring trap, and this page will not invent a circular or a list of package names. What can be said from the same RBI note is that an unknown app is already outside the precaution, and that a KYC pretext is already a named method. An app reached from a betting screen that asks for contacts, photos and broad permissions, and then for a further fee, should be treated as an unknown app. Uninstalling it and telling the bank about debits you did not make is the step the release supports. Naming a particular lending app here would be a claim this page has not verified from the regulator's text.
What this page will not do
It will not recommend a replacement app, a wallet, or a 'licensed' book. It will not quote a turnover, a loss rate, or a count of frozen accounts. Those figures are not in the press release opened for this article. The legal position of the game itself is a different page, the legal guide, and it does not collapse into one word. If the payments are tangled up with harm at home, the family guide is about the conversation and about Tele-MANAS, not about recovering a transfer.
Common questions
Should I enter my UPI PIN to receive winnings?
No. The RBI release of 28 January 2022 says that receiving money does not require a UPI PIN or a QR scan. A request that says otherwise matches the collect-request pattern it warns about.
A caller says the account will be blocked unless I update KYC. What does the RBI say?
The same release calls that threat a common method. It says not to use the offered link, and to use the bank website or branch.
Can MatkaFlash unfreeze an account?
No. This site has no access to a bank account. The release tells you to contact the bank or wallet and to block debit modes, including UPI, if you see a debit you did not make.
Is there a safe matka app?
This page does not name one. An unknown app is precisely what the RBI note says not to install.
Sources
Keep reading
 SafetyHow fix-game scams ask for a second feeHow a guaranteed matka number usually turns into an advance fee and a blocked withdrawal, and what to stop doing if you already paid.5 min read
 SafetyHow to spot a fake matka result site or appCopied results, fake live claims, paid groups and APK files. A checklist for leaving, not a list of sites to join.5 min read
 BasicsWhy guessing and fix ank do not workA matka chart records a draw that already happened. Fix ank lists and weekly jodis do not name the next independent draw.6 min read
 LegalIs satta matka legal in India?What the 1867 Act, Article 246 and the 2025 online gaming Act actually say. Not a yes, not a no, and not legal advice.7 min read